A merchant cash advance is usually written as a purchase of future sales rather than a loan, so many state usury caps do not apply to it on paper. A court can still treat an MCA as a loan when its terms, reconciliation rights, and personal guarantee look like debt, and some states now regulate MCA pricing directly. If you think your cost is unlawful, speak with a business attorney in your state before you stop payments.
What to do first
5 steps · most of it freeTick them off as you go. Saved only in this browser, never sent anywhere.
What Usury Means and Why MCAs Are Different #
Usury means charging more interest than the law allows. Most states set a maximum rate for loans, and violating that cap can make a loan void or let the borrower recover some of the interest paid, depending on the state.
An MCA is built differently on paper. You receive a lump sum now and agree to repay a larger fixed amount, usually through a share of your card sales or fixed debits from your bank account. The contract calls this a purchase of your future receivables. Because it is not labeled a loan, the usury cap that would apply to a loan often does not apply to the contract itself.
The label is a starting point, not the final answer. Courts look at what the deal actually does, and that is where the real questions begin.
How a Merchant Cash Advance Is Priced #
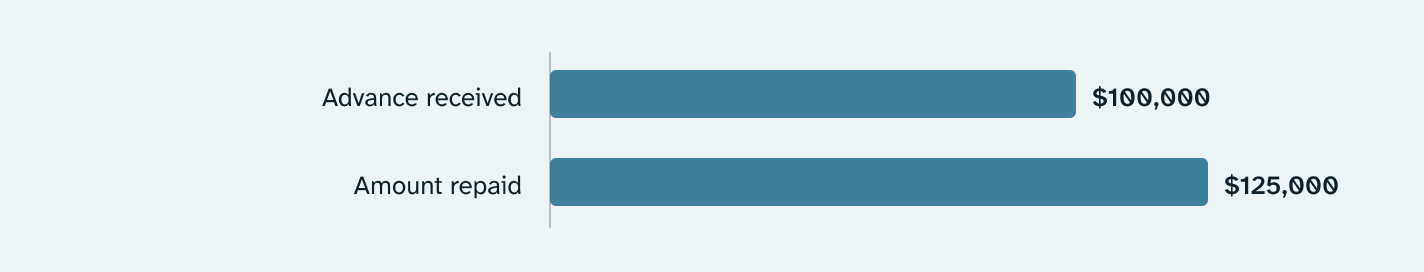
MCA contracts quote a factor rate, not an interest rate. A factor is a multiple applied to the cash you receive. At a 1.25 factor, a $100,000 advance means you repay $125,000 no matter how quickly you pay it off. Over an 8-month term, that same 1.25 factor works out to about 65–75% APR.
Because the factor ignores time, it can hide the real cost. Here is how the same 1.25 factor looks at different terms. These figures are illustrative, and the exact APR depends on how often payments are taken:
| Scenario (illustrative) | Amount repaid | Term | APR-equivalent |
|---|---|---|---|
| 1.25 factor on $100,000 | $125,000 | 8 months | ≈ 65–75% APR |
| Same 1.25 factor | $125,000 | 4 months | ≈ 110–120% APR |
The total dollars stay the same. The annual cost climbs as the term shrinks. This is why owners who compare MCAs only by factor often underestimate what they are paying.
When an MCA Can Be Treated as a Loan #
Courts can look past the label and examine the substance of the deal. Features that can push a judge toward treating an MCA as a loan include:
- A fixed repayment amount that does not really move with your sales.
- A right to full repayment even if the business closes.
- A personal guarantee from the owner.
- A right to demand the full balance immediately after a default.
- Reconciliation rights that exist only on paper.
If a court recharacterizes the contract as a loan, state lending and usury rules may apply. That can void interest above the legal cap or limit how the provider collects.
Outcomes vary by state and by facts. Some courts have upheld MCAs as true sales, and others have looked at the whole arrangement. No single clause decides the question.
State Rules That Can Change the Answer #
Some states now regulate MCA-style financing directly. Several, including California and New York, require providers to disclose specific pricing terms for certain commercial financing. Other states have passed or considered rules on registration, disclosure, or limits on specific practices.
These rules change often. Check your state's current law, and the guidance from your state attorney general or banking regulator. Also look at the contract's choice-of-law clause, because it can determine which state's rules a court applies. A business attorney in your state can tell you which rules apply to your situation.
Warning Signs in Your Contract #
Read your agreement for these items:
- A cost quoted only as a factor, with no APR-equivalent disclosed anywhere.
- A confession of judgment clause, which some states have banned for business financing.
- Daily or weekly debits that do not adjust to your sales, with no clear reconciliation process.
- A broad personal guarantee that reaches your home or personal assets.
- Automatic renewals, or "stacking," where a new advance pays off the old one at added cost.
- Fees beyond the factor, such as origination, broker, or weekly maintenance charges.
Finding one of these does not prove the contract is unlawful. It does mean the deal deserves a closer look from a professional.
Options if You Already Have an MCA #
If you already have an MCA, start with the facts. Get a written payoff statement, your payment history, and your sales records. Ask the provider to explain, in writing, how payments were calculated.
If your sales have dropped, request a reconciliation. Some providers will reduce debits; others will refuse. Either way, your written request becomes part of your record.
Do not stop payments on your own. Stopping can trigger default terms, a demand for the full balance, or a guarantee claim. Speak with a business attorney first, then decide on the next step with clear information.
When a Bank or SBA Loan Is the Better Tool #
Banks and SBA-backed lenders usually cost less and give you more time to repay. They also require more: time in business, stronger credit, full financial statements, and sometimes collateral. The process can take weeks or months.
An MCA works differently. It can fund in days, it often relies on your recent card sales or deposits rather than collateral, and approval does not depend as heavily on credit history. Those are real advantages if a bank will not approve you in time. They come at a higher cost.
| Option | Typical cost | Speed | What it needs |
|---|---|---|---|
| Merchant cash advance | Priced as a factor: 1.25 over 8 months, about 65–75% APR | Often days | Recent card sales or bank deposits |
| Bank term loan | Quoted APR, generally lower than MCA pricing for qualified borrowers | Often weeks | Time in business, credit, financial statements, sometimes collateral |
| SBA 7(a) loan | Rate capped under SBA rules; often the lowest-cost option if you qualify | Often months | Eligibility, detailed paperwork, sometimes collateral |
| Business line of credit | APR on the drawn balance, often variable; fees may apply | Often weeks | Credit history, revenue, sometimes collateral |
A bank or SBA loan is usually the right tool when you can qualify and have time to close. An MCA may be a fit when the alternative is a missed payroll and you understand the cost. Neither is right for every owner.
Can a merchant cash advance be usury? #
It can be challenged as usury, but the outcome depends on your state and your contract. The contract may be treated as a true sale of receivables, which usually avoids loan caps. It may also be recharacterized as a loan if its features look like debt. A business attorney can review the agreement and tell you whether a challenge is worth pursuing.
Is a merchant cash advance considered a loan? #
Usually not on paper, because the contract is written as a purchase of future sales. Courts can still treat it as a loan based on its substance. Fixed repayments, a personal guarantee, and a right to demand the full balance all push in that direction. The label is one factor among several.
How do I calculate the APR on a merchant cash advance? #
Start with the total repayment and the amount you received. Divide the cost by the amount, then annualize it over the actual repayment term, using a formula that accounts for how often payments are taken. As a worked case, a deal priced at 1.25 over 8 months comes to about 65–75% APR. Use a loan calculator that models your payment schedule, or ask a financial advisor to check the number.
What happens if I stop paying a merchant cash advance? #
Stopping payments usually triggers a default under the contract. The provider may demand the full remaining balance, debit your account where the contract permits, and pursue a personal guarantee. Some contracts include confession of judgment clauses, which some states restrict. Talk with a business attorney before stopping payments, and ask for a written payment plan if you need time.
Can I sue an MCA provider for charging too much? #
You may have a claim if the contract was recharacterized as a loan and exceeds your state's legal limit, or if the provider violated a state disclosure rule. Claims depend on specific facts, deadlines, and the choice-of-law clause in your contract. A business attorney in your state can evaluate your agreement and explain what recovery is realistic.
Where an MCA fits, and where it doesn't #
An MCA can be a practical bridge when you need cash fast, you understand the full cost, and you have a clear plan to repay. It is a poor fit when your revenue cannot cover the daily or weekly debit, when you are stacking advances, or when you have not seen the APR-equivalent in writing. If you want to compare your numbers against a bank or SBA option before you commit, start your request.
Sources #
Where to from here
This guide is general information, not advice for your situation. Costs are typical ranges, not offers; the terms that apply to you are only those in an agreement you sign. If a lawsuit, judgment or lien notice has arrived, get an attorney involved. How this site is paid.